Learning Center · Storm and Insurance
Storm Damage and Insurance
Nine plain-language guides for Texas homeowners on what to do when hail, wind or a leak hits the roof, how the insurance process works, and how to avoid the mistakes that are hardest to undo.
Updated November 14, 2026
In the order you need them
Every storm and insurance guide, in order
Start Here
The short version
What to do when a storm hits your roof
Take photos from the ground first, dated by your phone, before anyone else looks at the damage, using the photo checklist, and read what to do after hail or wind damage for the order of decisions. Do not sign anything at your door, and learn the warning signs of a storm chaser before one knocks. Your policy sets the deadlines for reporting a claim and for filing suit, and Texas lets a policy make them short, so find them early. Tell your insurer about the damage in writing and keep a log of every call, and read how the hail claim process works before the adjuster visits. A documented inspection gives you your own record of the roof to set beside whatever the adjuster writes down.
What to do first: take your photos today, find the deadline wording in your policy, and report the damage to your insurer in writing.
Nine Guides
Nine guides, one clear path
Nine guides on what to do, what to photograph, hail, wind, leaks, roof age and deductibles, claims and storm chasers.
After Hail or Wind Damage
What to do, in order: stay off the roof, photograph from the ground, tell your insurer in writing, and what not to sign at the door.
Start HereWhat the Storm Left Behind
The photo and record checklist: what to photograph outside, on the roof from the ground, and room by room inside.
Photo ChecklistHail Damage Atlas
What hail does to shingles, metal, tile and flat roofs, and the five things mistaken for hail damage.
IdentificationHail History by Address
Type in a Texas address to see each day since October 2020 that NOAA radar recorded hail of 3/4 inch or larger nearby.
Address LookupHail Damage and Insurance Guide
The Texas hail claim from start to finish, including RCV against ACV, depreciation, deadlines and SB 458.
Claim ProcessDate of Loss vs Date of Discovery
The storm date, the day you found the damage, how long Texas policies usually give you to report, and who decides the date.
Claim ProcessHow to Spot a Storm Chaser
The warning signs, the papers never to sign at the door, and the checks that show who a contractor is.
Contractor SafetyWind Damage to a Roof
What wind damage looks like, what lifts shingles, how it is documented slope by slope, and what an adjuster looks for.
WindRoof Leak First Steps
The first hour of a leak: protect the room, find the source, tarp it right, and photograph before cleanup.
LeaksRoof Age, ACV and Deductibles
How roof age changes a Texas claim: RCV against ACV, recoverable depreciation, percentage deductibles and cosmetic exclusions.
Policy TermsWhat We Do
What The Roof Shepherd does after a storm
We advise, educate, document the roof and submit supplements, and we never negotiate or settle your claim.
A documented inspection
We inspect the roof and record what is there. You get dated photos, damage marked where it is found, and plain notes that separate storm damage from wear, written the way a claim review reads them. The record is yours to keep and to use with any insurer or contractor. See how insurance documentation works.
Your options and rights, in plain language
We advise and educate you on your options and rights, document the roof, and submit documented supplements. We are not a public adjuster and never negotiate or settle a claim for you. We send a supplement when your insurer’s estimate leaves out work the roof needs. You make the decisions, and your insurer settles with you.
What it costs
Within about 30 minutes of Round Rock an inspection is $50, and $100 out to about an hour, paid at the visit, booked by call or text at 512-575-5052 or online; either way it includes a written report. Farther out, the price is set by drive time and you hear it first, and we serve all of Texas. Read what a documented roof inspection covers, then the inspection cost page for the details. When you are ready, tell us what happened through Get Help, or call or text 512-575-5052.
When You Are Ready
When you are ready
Insurance Documentation
Here is how we help. When the storm turns into a claim, the roof record comes first. We advise and educate you on your options and rights, document the roof, and submit documented supplements. We are not a public adjuster and never negotiate or settle a claim for you.
Or call or text 512-575-5052.
Field Photos
On the job
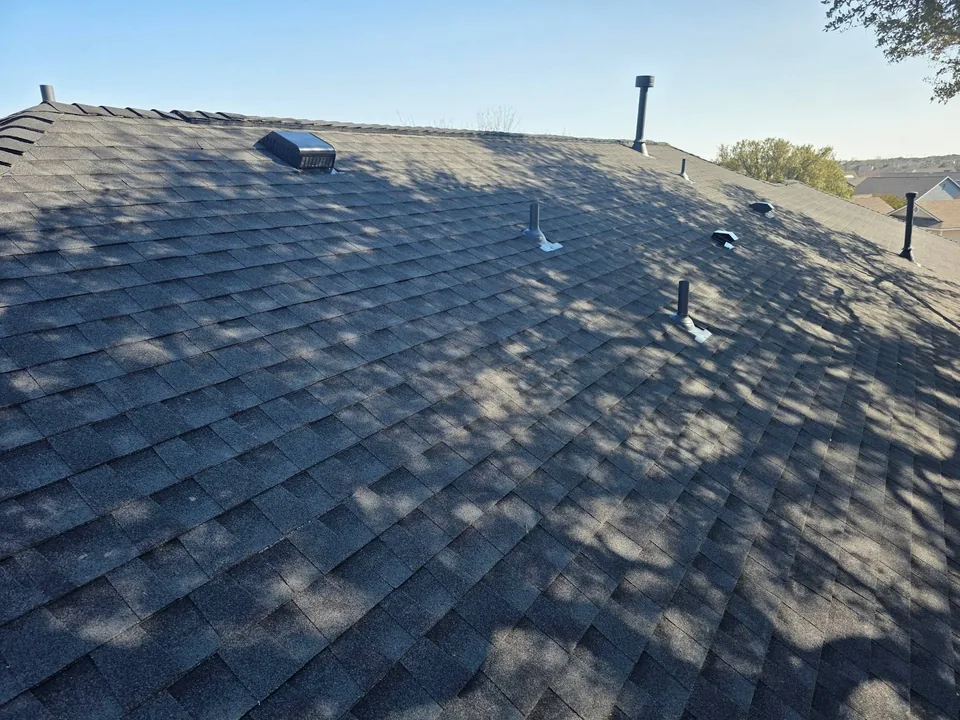
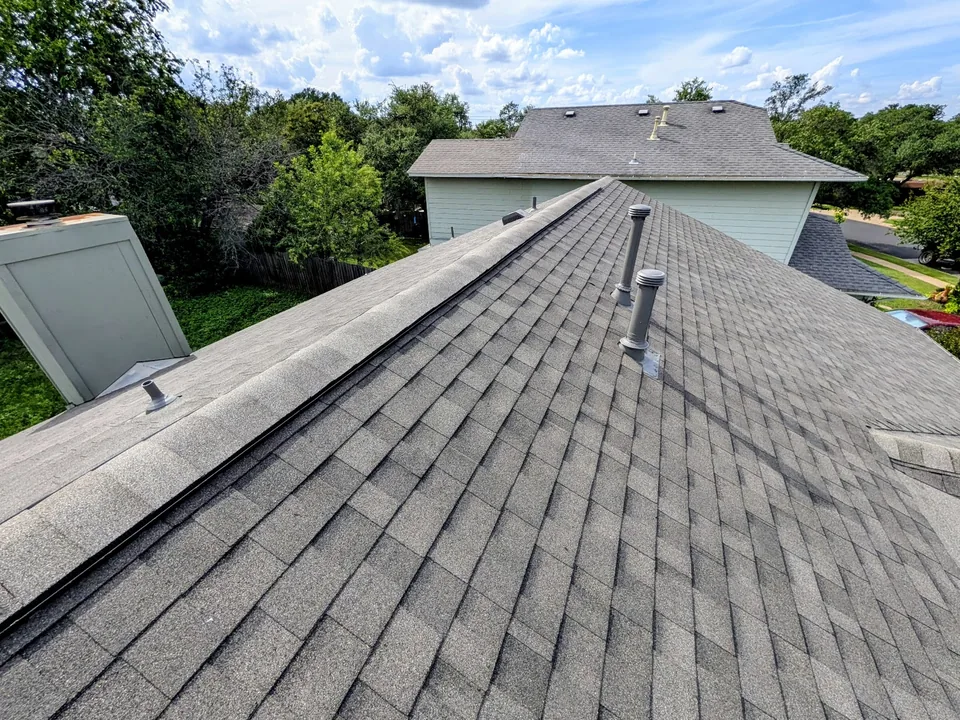
Photos from roofs we have worked on. Select one to enlarge it.
Field Videos
From the field
A real job, filmed and explained.
Real Hail Roof Inspection in Manor Texas
The signs of hail damage explained during a Manor inspection, what to look for, what it means, and how it is documented.
Watch on YouTubeCommon Questions
Questions homeowners ask after a storm
How long do I have to file a hail damage claim in Texas?
Plan on two years or less from the date of loss, and treat that as your deadline. Texas does not publish a filing deadline of its own, so the deadline that binds you is the one in your policy, and the law lets that policy be short. Tex. Civ. Prac. & Rem. Code § 16.070 permits a contract to cut the time to sue down to two years and makes anything shorter void, and Texas homeowners policies routinely sit on that two-year floor. The time to report damage can be shorter still: § 16.071 voids a notice condition of less than 90 days, and policies set the window, so read the “Suit Against Us” condition in your own policy for the exact number. This is general information about deadlines, not advice about your claim, and a deadline question with money on it is worth a licensed Texas attorney.
Should I call my insurance company or a roofer first?
Document first, then report. Spend about 30 minutes taking dated photos from the ground, then tell your insurer about the damage in writing, because an email creates a record of what you reported and when. The Texas Department of Insurance tells homeowners to “call your insurance agent or company as soon as possible to report property damage”, so do not let photographing turn into waiting. The photo and record checklist lists every surface worth a photo. You do not need a roofer to report a claim, but a documented inspection gives you your own record of the roof before anyone with a stake in the outcome writes theirs.
What is the difference between RCV and ACV on a roof policy?
RCV, replacement cost value, pays what it costs to replace the roof with similar materials, but in two payments. The insurer first pays the amount minus withheld depreciation, then releases that holdback after you finish the repairs and send in proof. ACV, actual cash value, subtracts depreciation for good, so no second payment comes. Your declarations page says which one you have, and some carriers move older roofs to ACV when a policy renews, so check it before a storm, not after.
What does a documented roof inspection give me?
A dated record of the roof’s real condition that you own: slope-by-slope photos, damage marked where it is found, the roofing material identified, and plain notes that separate storm damage from age and wear. It is complete whatever it shows, so it is as honest about what is not storm damage as about what is. Within about 30 minutes of Round Rock an inspection is $50, and $100 out to about an hour, paid at the visit, with the written report; book by call or text at 512-575-5052 or online. Farther out, the price is set by drive time and you hear it before anyone drives out. You can take the record to any insurer or contractor, or keep it if you decide not to claim.
Can The Roof Shepherd negotiate my insurance claim?
No. The Roof Shepherd is not a public adjuster. Texas Insurance Code 4102.163 bars a contractor from acting as a public adjuster, which includes negotiating or settling a claim for the homeowner, on any property it works on or may work on. We advise and educate you on your options and rights, document the roof, and submit documented supplements. We are not a public adjuster and never negotiate or settle a claim for you. A supplement goes in when your insurer’s estimate leaves out work the roof needs. You make the decisions, and your insurer settles the claim with you. Only a licensed public adjuster or attorney can represent you in the claim itself.
What is a storm chaser?
A storm chaser is a roofing crew that follows hail from town to town, often arriving within days of a storm, and leaves when the work is done. The risk comes later, with a workmanship problem a year or two on and a company that has no local address and a phone number that no longer works. The warning signs are pressure to sign the same day, papers that transfer your claim rights, and a local address you cannot verify.
Should I be there when the adjuster inspects the roof?
The Texas Department of Insurance tells homeowners to “try to be there when the adjuster visits so you can point out all damage”. Having your own dated photos in hand makes that easier, because you can show what you saw before the visit instead of relying on memory.
Hail fell near me. Does that mean my roof is damaged?
Not by itself. A radar or storm report shows that hail fell nearby on a date, not what it did to your roof. The hail history lookup lists the days radar recorded hail of 3/4 inch or larger near an address, and the hail damage atlas shows what damage looks like on each roofing material and what is often mistaken for it. A roof inspection settles it.
Keep Learning